 Fundraising Fox

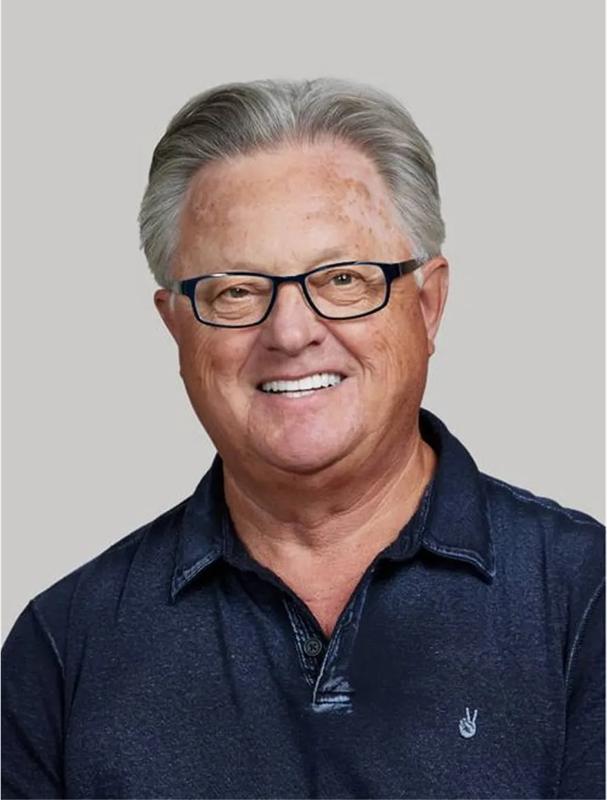
Chris Dixon
InvestorFounderFounder, Managing Partner at a16z crypto (Andreessen Horowitz) · Co-founder at Founder Collective · Co-founder at a16z Speedrun
San Francisco, CA
Writes $10M – $60M checks · typically $20M
Foundeda16z SpeedrunFounder Collective
Midas 2019 · #67Midas 2020 · #29Midas 2021 · #7Midas 2022 · #1Midas 2023 · #25Midas 2024 · #6Midas 2025 · #10Midas 2026 · #36
Find your path to Chris
Sign up to see every warm intro you have to Chris
- Paths you didn't know you had: your email and LinkedIn already hold routes to Chris. We find them for you
- 2nd- and 3rd-degree connections: the friend-of-a-friend routes that take hours to manually find through your inbox or LinkedIn
- Answers now, not in days: momentum is everything in a raise. Skip asking around whether someone knows someone
Days of research, done the moment you sign in, with every route ranked by how warm it is.
Photo: TechCrunch, CC BY 2.0, via Wikimedia Commons ↗
About
Chris Dixon co-founded the startups SiteAdvisor and Hunch before joining Andreessen Horowitz in 2013, where he built and leads a16z crypto, the firm's multi-billion-dollar web3 arm. His investments include Coinbase, Uniswap, and OpenSea, and he ranked first on the Midas List in 2022. His book Read Write Own makes the case for blockchain-based networks as the internet's next architecture.
Invests in
AI & Machine LearningBiotechConsumerCreator EconomyCrypto & Web3CybersecurityDefense TechDeveloper ToolsFintechGamingMarketplacesSocial
Beyond investing
- Founded
- Co-founded the internet security company SiteAdvisor, which was acquired by McAfee. Co-founded the AI startup Hunch, which was acquired by eBay. Dixon co-founded SiteAdvisor, a web-security startup acquired by McAfee in 2006. Dixon founded Hunch in 2009 with Caterina Fake and Tom Pinckney; it was acquired by eBay in 2011. Dixon co-founded Founder Collective, a seed venture fund. Dixon described a roughly $40 million fund whose entire business was seed investing, with active entrepreneurs leading investments and sharing profits. He argued smaller funds reduced pressure to overcapitalize companies and made smaller founder-preferred exits acceptable. Dixon wrote that SiteAdvisor's initial $2.6 million round at a $2.5 million pre-money valuation transferred 56% to investors, included milestones and an unused third tranche, while the company spent under one-third of total money raised. This is first-person recollection, useful but not audited cap-table evidence. Crypto Fund I launched in 2018 with $350 million. The current official profile says five dedicated funds have raised more than $9.8 billion, expanding from venture equity into networks, tokens, applications, infrastructure and policy support.
- Education
- Studied at Columbia University (BA, Philosophy) Studied at Harvard Business School (MBA) Studied at Wesleyan University
- Communities
- Dixon grew up in Ohio.
- Awards
- Wrote a book titled Read Write Own, published in 2023. Fortune called Dixon 'the world's top crypto investor' in 2022. Dixon won the 2012 Crunchies Angel of the Year award and ranked first on the 2022 Forbes Midas List, primarily reflecting Coinbase and crypto-fund results. Awards are industry/media recognition, not audited lifetime performance.
- Hobbies
- Dixon started programming as a kid and worked as a professional programmer at high-speed options trading firm Arbitrade after college.
- More
- Dixon writes about entrepreneurship and investing on Substack and previously on Medium and cdixon.org. Dixon grew up in Springfield, Ohio, one of four sons of two Wittenberg University English professors, and attended Atari user-group meetings at Wright-Patterson Air Force Base. Exact birth date and full childhood chronology are not established by primary records. He began programming as a child and later worked professionally at options-trading firm Arbitrade, giving him an operating and technical background beyond his philosophy and business degrees. SiteAdvisor automatically tested and rated websites for malware, spam and related hazards. Technical reporting credited Wyatt and Pinckney with core software development; Dixon was CEO and co-founder, so the product should not be portrayed as his sole technical creation. McAfee announced the acquisition April 5, 2006. A subsequent company filing reported approximately $60.8 million cash to former shareholders plus $9.3 million contingent service payments; neither figure is Dixon's personal proceeds. Hunch combined questionnaires and web/social data to predict affinities for products and other subjects. Dixon shared founder credit with Tom Pinckney, Matt Gattis and, in contemporaneous accounts, Caterina Fake. eBay acquired Hunch on November 21, 2011 and retained its New York team. Reuters and eBay said price was undisclosed; approximately $80 million was contemporaneous source reporting, not an official transaction value. TechCrunch's 2013 award account listed more than fifty angel investments and distinguished personal activity from Founder Collective investments. Current first-party biography conservatively highlights Kickstarter, Pinterest, Stack Overflow and Stripe. a16z identifies Dixon as lead for its Oculus Rift investment; Facebook acquired Oculus in 2014. Exact fund check, ownership and Dixon economics are not reconstructed. a16z says Dixon led its first Coinbase investment in 2013; Coinbase went public by direct listing in 2021. Dixon later said he served on the board for a long period, but exact appointment and departure dates remain unresolved. Forbes reported, citing a knowledgeable source, that Crypto Fund I reached approximately $6 billion in realized and unrealized gains on $350 million at year-end 2021, a 17.7x multiple. Other reporting said the flagship fund fell roughly 40% in the first half of 2022. Private marks, realized distributions and later performance are not public. Dixon's signed 2021 thesis praised Axie's growth, economic freedom and Ronin infrastructure. The subsequent token/economy collapse and Ronin bridge exploit make it a material mixed-to-failed outcome; exact a16z loss or current ownership is not disclosed. Dixon led the 2021 Series A thesis and took over a16z's board seat from Katie Haun in 2022. OpenSea later reduced staff amid lower NFT activity and competition; private valuation is not a realized return. He supports SEC regulation, disclosures and lockups while a project remains controlled, followed by CFTC commodity oversight after objective decentralization thresholds, plus federal oversight of intermediaries. Critics question whether decentralization can be measured neutrally and whether the framework benefits token investors such as a16z. Dixon publicly advocates market-structure legislation, token rules and reduced regulatory uncertainty while leading more than $9.8 billion of dedicated crypto funds. The alignment is economically important and should be disclosed, but does not establish improper influence or invalidate the policy arguments. Random House published the book January 30, 2024. It presents blockchains as computers rather than casinos and the internet's next ownership architecture. Critical reviewers disputed its scalable non-speculative examples and portfolio disclosures; Vice reported the New York Times list marked it for included bulk purchases, while a16z said the Times had vetted sales under its rules.
Mentioned above: the Columbia University mafia → · the Founder Collective mafia →
From Chris's own website — common ground for a warm intro.
Co-founder at Founder Collective
Intro paths
In turn, Chris can intro founders to Founder Collective's investors below.
Founder Collective's investors · 5
Co-founders at Founder Collective
Co-founder at a16z Speedrun
Intro paths
In turn, Chris can intro founders to a16z Speedrun's investors below.
a16z Speedrun's investors · 14
Co-founders at a16z Speedrun
Investments
Investor
42Floorsa16z crypto managed portfolioAdimAirwareAptosAutographAvalancheAxieBehanceBitskiBloomNationBloomreach, Inc.BondsyBonfire StudiosBuzzFeedCanonicalCatenaCirculateCo:CreateCoinbaseDapper LabsDfinitydYdXEnvoyEveFiftyThreeFlatiron HealthFluidinfoFoursquareFoursquare, Hipmunk, Dropbox, Codecademy, Optimizely, TrialPay, OMGPOP and SkypeFriends With BenefitsFundersClubHeyzapHunchImprobableKetone-IQKickstarterKickstarter, Pinterest, Stack Overflow and StripeKitchensurfingKnewtonLibermans CoMakerBot, IFTTT, Milo, GroupMe and BuzzFeedManifoldMeddikMerit SystemsMiloMSquaredMyVRNansenNEAROculusOculusOMGPopOpenseaOptimismOptimizelyOysterPandoDailyPhiPicturelifePolychainPolyworkPoseidonProof of PlayRebelMouseRedbeard VenturesRescaleShapewaysShield USDTSiftSilvercarSingularity 6SkySafeSmartthingsSoylentSpruceStack OverflowStripeTalosThe Data FoundationUniswap, Maker, Compound and MorphoUniteVoxerYuga LabsYuppZipline International
Per curated public sources.
Controversies & responses
Where Chris has drawn public criticism — with what happened, their response, and the criticism itself, side by side.
▶Token voting power challenged decentralization claims2021
- What happened
- Controversial Uniswap votes prompted criticism that a16z and delegates held excessive influence and lacked transparency. a16z responded by publishing delegation principles requiring delegate independence and greater disclosure. This was a firm governance issue under Dixon's practice leadership, not proof he directed each vote.
▶Jack Dorsey disputed venture ownership in web32021
- What happened
- Dorsey argued users did not own web3 because VCs and LPs controlled it, implicitly targeting a16z. Dixon answered that code, data and ownership were open and that a16z owned very little; in a later interview he estimated average early ownership near 3% and Ethereum exposure far below 1%. Those figures were informal, not audited disclosures.
Founder fit — who Chris backs
Best fit is a technically credible or deeply domain-embedded founder who can explain years of prior attempts, dead ends and enabling changes; has built a working product or difficult infrastructure; demonstrates founder-market fit and earned secrets; and wants to create an open network or major new computing category over a decade. Dixon's signed work favors pragmatic teams who combine ambitious architecture with excellent developer or consumer experience, persist when a category is unfashionable and can recruit unusually strong collaborators. Crypto founders fit best when decentralization is necessary rather than decorative, token distribution aligns users and builders, governance can become genuinely independent, security is first-class and the product supplies durable utility beyond asset appreciation.
Likely weak fits include shallow trend-following, a token added to an otherwise centralized product, founders unable to explain prior attempts, products whose only demand is price appreciation, opaque insider allocations, short unlocks, governance theater, unaudited critical infrastructure, fragile bridge or custody design, excessive take rates, and pitches that rely on favorable legislation rather than users. His record also counsels against extrapolating peak token prices or NFT volume into durable value. Political agreement is not a documented investment requirement and should not be inferred.
How to pitch
Begin with the founder's path into the problem, the earned secret and a map of the idea maze: what has been tried, why it failed and what technical or social change makes this attempt different. Show the product, developer traction or user behavior; explain network effects and the path from initial application to broader platform. If crypto is involved, state why a normal database or company is insufficient, who receives tokens and when, how insiders are locked, how governance becomes independent, which rights users actually own, and how security, compliance and consumer protection work. Quantify take rates and participant economics. Identify the relevant a16z crypto partner and vehicle rather than assuming Dixon personally leads every deal. Address failure modes, speculation, regulation, bridge/custody risk and centralization criticism directly.
Stages: personal angel historically, seed through Founder Collective historically, Series A and early venture, growth through a16z and dedicated crypto vehicles, token and network investments, follow-on financing, private-company board governance, public-network governance through delegated tokens · Sectors: blockchain infrastructure and Layer 1/Layer 2 networks, crypto exchanges, custody and wallets, decentralized finance and payments, stablecoins and tokenized assets, NFTs and digital ownership, gaming and virtual worlds, decentralized social and media, creator economics, developer tools and open-source protocols, AI and creator compensation, consumer internet and marketplaces, virtual and augmented reality, security, 3D printing and frontier hardware, professional networks
Editorial inference from Chris's portfolio, writing and public record — not a published mandate.
Investment themes
10 documented themes from Chris's essays, talks and portfolio, grouped by what they say about founders.
▶Founders & company building1
Founder-market fit precedes product-market fit2011
Founders choose markets before product-market fit exists, so deep understanding and a life pattern that personifies the product can be the strongest early predictor.
For founders: Show why your history, skills, relationships and obsession create non-transferable insight into this market.
▶More themes6
Navigate the idea maze2013
Strong founders understand the history, branches, failed attempts and future decisions around an idea rather than presenting it as a blank field.
For founders: Walk through prior companies, technical approaches, regulation and dead ends, then identify the branch newly available now.
Pitch the team through what it can build2010
At early stage the team is more durable than the initial idea; a prototype is evidence that founders can execute, not merely proof an abstract product is possible.
For founders: Demonstrate technical and product agency with something built and explain how the team learns.
Ownership constrains corporate take rates and rug pulls2021
Tokens and open standards can let users retain assets and exit applications, reducing a platform's ability to change rules unilaterally. Concentrated token ownership can recreate the same power problem.
For founders: Quantify take rates, portability and governance rights and disclose where insiders still retain control.
Rules should evolve with decentralization2024
Dixon advocates securities-style disclosures and lockups while insiders control a network, then commodity oversight after measurable decentralization, alongside anti-fraud regulation for intermediaries.
For founders: Build compliance, disclosure, insider lockups and a credible decentralization roadmap into the product rather than treating enforcement uncertainty as a moat.
Developer activity matters more than short-term price2022
During the crypto drawdown Dixon said entrepreneurs and developers were his core metric. It is a useful long-horizon indicator but does not by itself establish product demand, token value or fund performance.
For founders: Show sustained builders and deployed applications, then connect them to user retention and viable economics.
Avoid unnecessary founder dilution2010
Dixon's SiteAdvisor experience led him to favor right-sized seed rounds, staged learning and investor structures aligned with founder-preferred outcomes.
For founders: Raise enough to reach a value-inflecting milestone and understand ownership, tranche and governance terms rather than optimizing for headline round size.
▶Governance & network states2
Read, write and own are successive internet architectures2024
Open protocols democratized information, corporate networks democratized publishing, and blockchain networks could add user ownership and persistent property rights. This is Dixon's thesis, not an established historical inevitability.
For founders: Specify the ownership right, interoperability and governance advantage the network provides in practice.
Delegation must be independent and transparent2021
After criticism of DeFi votes, a16z advocated delegates free from token-holder direction plus clearer disclosure of parties, terms and relationships.
For founders: Design delegation contracts, disclosure, conflicts and replacement processes before token voting becomes contentious.
▶Money, markets & macro1
Distinguish computers from casinos2024
Dixon argues blockchains are programmable computers and networks even though token markets also enable speculation. Critics respond that speculative demand remains central to many deployed systems.
For founders: Prove useful computation, coordination or ownership independent of rising token price and design against casino dynamics.
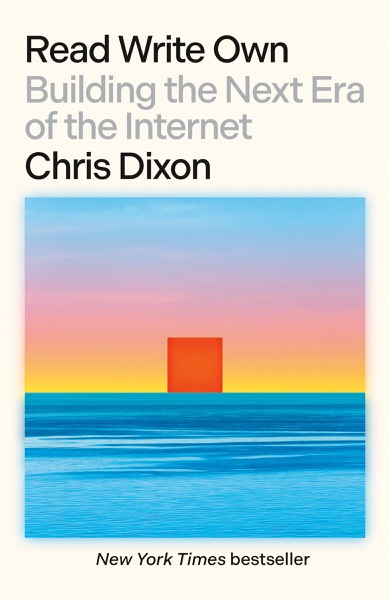
Books by Chris Dixon
Podcasts & interviews
featuring Chris DixonWho Will Own the Internet? a16z's Chris Dixon on AI and Crypto
a16z
Marc Andreessen and Chris Dixon: Why America Needs Clarity
a16z crypto
Chris Dixon - Why Crypto Is Still Critical to Our Future
The Next Big Idea Podcast
a16z Crypto Managing Partner Chris Dixon Live on TBPN
TBPN
Chris Dixon - Entrepreneur, Investor, Cryptocurrency and Web3 ...
Scott D. Clary - Success Story Podcast
Chris Dixon Fireside: The Next Era of the Open Internet | Chris Dixon - a16z crypto
ETHDenver
6 more appearances
- Andreessen Horowitz GP Chris Dixon on Crypto, AI, and Web32024-02-27
- A16z Crypto’s Chris Dixon on How Blockchains Can Save the Internet - Ep. 6012024-01-30
- A16z Crypto's Chris Dixon Sees a Crypto 'Renaissance'2024-01-30
- Read Write Own: A New Era of the Internet with Chris Dixon2024-01-30
- Read. Write. Own. | Chris Dixon2024-01-29
- Chris Dixon | a16z Crypto Startup School | Before the iPhone, it was hard for developers to build useful apps. Now blockchain computers are freeing up developers to work on the layer of the stack... | By TechCrunch
Writing
All posts ↗Dixon has recently written about crypto and web3 as a path to an ownership-based internet, including announcing his book Read Write Own, and about how NFTs reshape creator economics and how new technologies enable brand-new activities rather than just improving old ones.
Dixon announces his book Read Write Own, which argues blockchains enable an ownership era of the internet and explains their applications, policy issues, and place in internet history.a placeholder
Dixon argues NFTs improve creator economics by removing intermediaries, enabling granular price tiering, and turning users into owners, reviving Kevin Kelly's 1,000 true fans concept.a placeholder
Dixon distinguishes technologies that improve existing activities from those enabling entirely new ones, arguing the latter category ultimately has more impact but takes longer to emerge.a placeholder
Colleagues at a16z crypto
Network41

▶29 more connections
Bowen Liu · scoutBryan Faust · scoutBryan Kim · scoutCaroline Goggins · scoutCarra Wu · scoutChris Kurdziel · scoutConnie Chan · scoutConnor McCarthy · scoutDaisy Wolf · scoutDan Wendlandt · scoutDaniel Chen · scoutDaren Matsuoka · scoutDavid George · scoutDavid Haber · scoutDavid Rutter · scoutDavid Ulevitch · scoutDovey Wan · scoutEddy Lazzarin · scoutEileen Wu · scoutElizabeth Harkavy · scoutEmma Cooper · scoutEric Alby · scoutEric Friedman · scoutFrank Chen · scoutGabriel Vasquez · scoutGary Vaynerchuk · scoutGeoffrey Woo · scoutRobert Swan · scoutThomas George · scout
Investors connected to Chris in public investor directories — a warm-intro map.
Frequently asked questions
- Who is Chris Dixon?
- He is a programmer, SiteAdvisor and Hunch co-founder, Founder Collective co-founder, Andreessen Horowitz general partner, founder and managing partner of a16z crypto, early-stage investor and author of Read Write Own.
- What did he study?
- He earned B.A. and M.A. degrees in philosophy from Columbia and an MBA from Harvard Business School. A professional database dates the M.A. to 1995 and MBA to 2003, but official biographies do not publish full attendance dates.
- What companies did he found?
- SiteAdvisor, Hunch, Founder Collective and a16z crypto, all with distinct co-founders or institutional contexts. SiteAdvisor and Hunch were operating companies; Founder Collective and a16z crypto are investment organizations.
- What were his operating exits?
- McAfee acquired SiteAdvisor in 2006; eBay acquired Hunch in 2011. SiteAdvisor filing consideration and Hunch's reported price are company-level economics, not Dixon's personal proceeds.
- Which pre-a16z investments are strongest?
- His first-party biography highlights Kickstarter, Pinterest, Stack Overflow and Stripe. Contemporaneous award reporting lists more than fifty angel investments and separately identifies Founder Collective deals, but exact entities and checks remain incomplete.
- Which a16z investments are directly attributable to him?
- Oculus and Coinbase are explicitly described as Dixon-led. Signed announcements and boards provide direct evidence for OpenSea, Optimism, Bitski, Singularity 6, Polywork, Dapper Labs and Axie Infinity at varying strengths. Other a16z crypto holdings should remain vehicle-level without specific evidence.
- Did he personally lead every a16z crypto deal?
- No. He founded and leads the practice, but team members and funds make many investments. Portfolio status proves managed-vehicle exposure, not Dixon's personal sourcing, check, board role or token vote.
- What does read-write-own mean?
- It is Dixon's framework in which open networks first enabled reading, corporate networks added mass publishing, and blockchain networks could add durable user ownership, portability and economic participation. It is an investment thesis, not a settled forecast.
- How should a founder pitch him?
- Explain founder-market fit and earned secrets, walk through the idea maze, show what you built and why now, and quantify user and participant value. For crypto, prove why decentralization is necessary and address token distribution, insider lockups, governance, security, regulation and non-speculative demand.
- What are the major successful outcomes?
- SiteAdvisor and Hunch were acquired; Oculus was acquired by Facebook; Coinbase directly listed; and several personal or Founder Collective bets had acquisitions or public outcomes. Fund returns and personal proceeds remain mostly private.
- What failed or mixed investments belong in the record?
- Axie Infinity's economy and Ronin security failure, OpenSea's post-boom retrenchment, BuzzFeed's poor post-listing performance and broad token drawdowns are material. They differ in attribution and are not all liquidations; exact fund losses are not public.
- How did a16z crypto perform?
- Forbes reported Crypto Fund I at about 17.7x on realized and unrealized value at year-end 2021; reporting then said the flagship fund fell roughly 40% in the first half of 2022. These are point-in-time private marks, not current audited net returns.
- What is the token-governance controversy?
- Critics argued a16z and its delegates had excessive influence over Uniswap governance and insufficient transparency. The firm responded with principles for independent delegation and disclosure. Practice leadership makes the issue relevant to Dixon, but reviewed evidence does not show he personally directed each vote.
- What does he advocate in crypto regulation?
- Clear federal oversight, tailored disclosures, anti-fraud and insider-trading rules, long founder and VC lockups, SEC treatment while insiders control a network, and CFTC commodity oversight after sufficient decentralization. Critics dispute the framework and its beneficiary incentives.
Founder mafias
Columbia University mafia606
Also came through, then founded or led a company.


Andreessen Horowitz mafia97
Also came through, then founded or led a company.

Founder Collective mafia16
Also came through, then founded or led a company.
Improbable mafia14
Also came through, then founded or led a company.
BuzzFeed mafia7
Also came through, then founded or led a company.

About this profile. Compiled from public sources — a16z crypto's own website, press coverage and public professional profiles — and summarised by Fundraising Fox; every fact is kept with where it came from. Spotted an error, or would rather not be listed? Email privacy@fundraisingfox.com · How we build profiles · Your rights